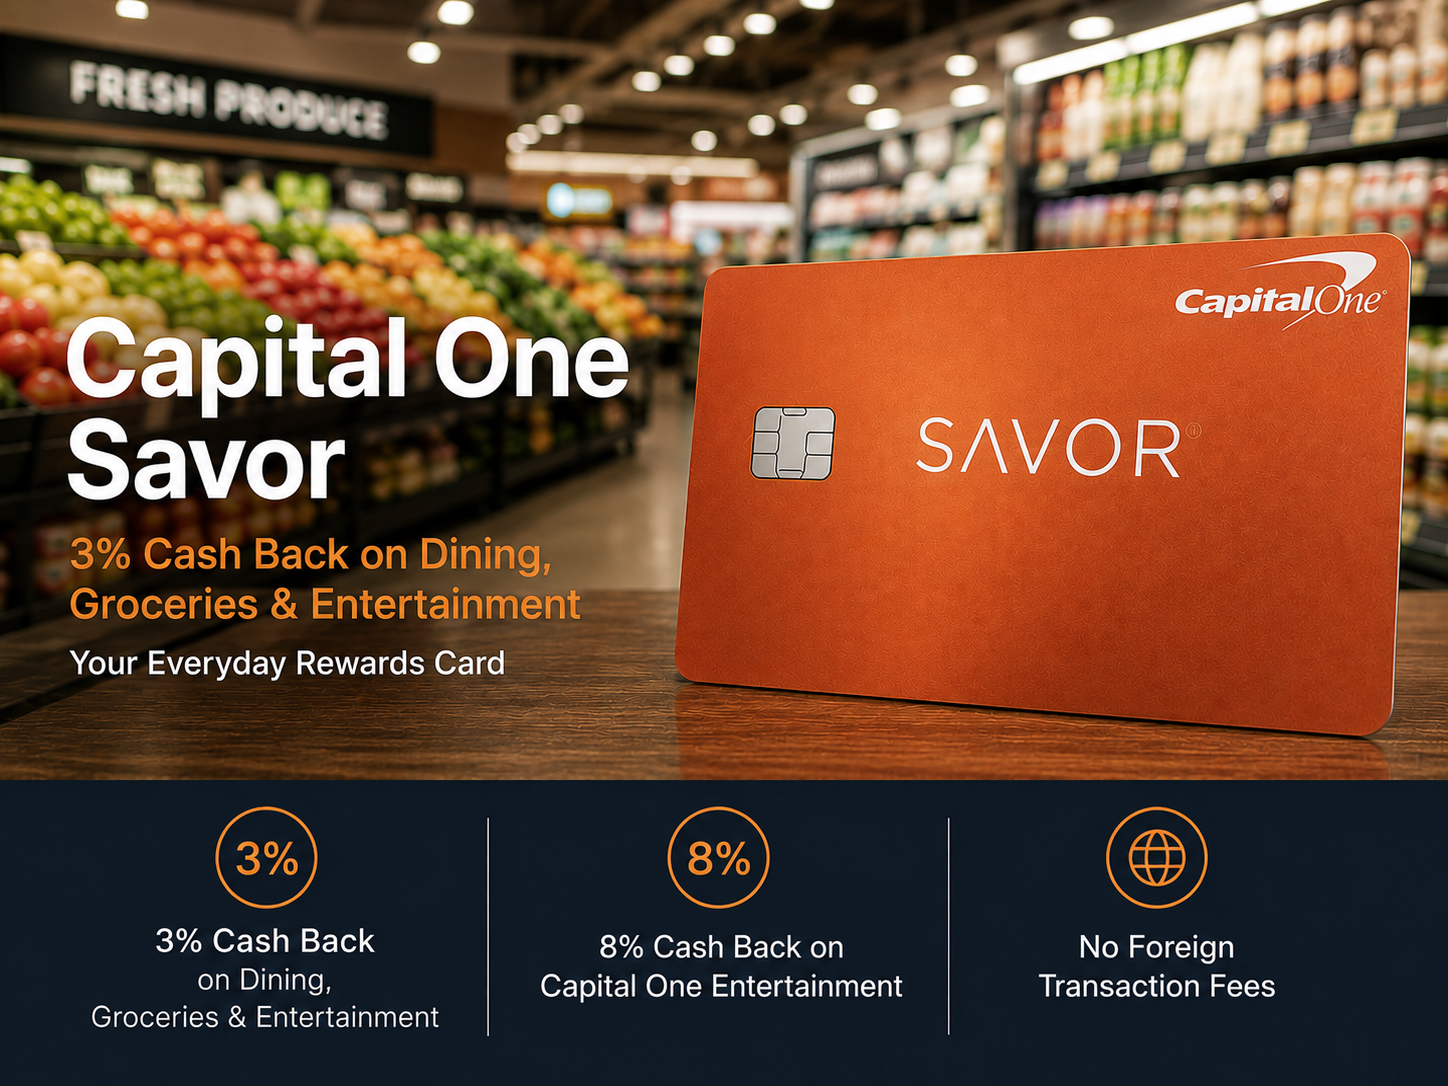

The Capital One Savor Cash Rewards Credit Card is a no-annual-fee cash-back card designed for everyday spending, especially dining, grocery stores, entertainment, and popular streaming services.
With a $0 annual fee and 3% cash back in several popular everyday categories, Savor is also an excellent companion to a Venture card. Savor can cover bonus categories while Venture handles everyday non-bonus spending and Capital One Miles.
Best For: Everyday spending + pairing with a Venture card
👉 Apply for the Capital One Savor Rewards Credit Card
Capital One Savor Benefits
| Benefit | Capital One Savor |
|---|---|
| Best For | Everyday spending + Venture pairing |
| Annual Fee | $0 |
| Dining | 3% Cash Back |
| Grocery Stores | 3% Cash Back |
| Entertainment | 3% Cash Back |
| Popular Streaming Services | 3% Cash Back |
| Capital One Entertainment | 8% Cash Back |
| Capital One Travel | 5% on eligible hotels, vacation rentals, rental cars & activities |
| Other Purchases | 1% Cash Back |
| Foreign Transaction Fee | $0 |
| Rewards Type | Cash Back |
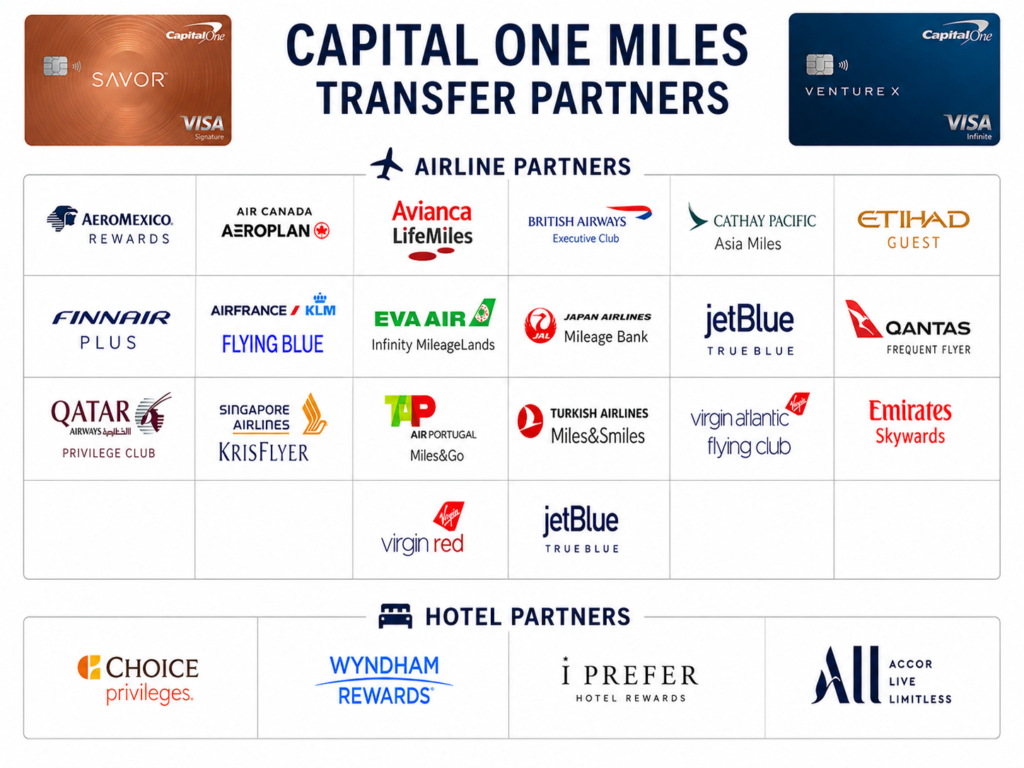
| Airline / Hotel Transfers | Savor does not directly transfer to travel partners |
Savor is best suited for consumers who spend heavily on dining, groceries, entertainment, and streaming—or already have a Venture card.
Best Card Pairing: Savor + Venture X
The card I recommend pairing with Savor is the Capital One Venture X Rewards Credit Card.
| Spending Category | Best Card | Rewards |
|---|---|---|
| Dining | Savor | 3% |
| Grocery Stores | Savor | 3% |
| Entertainment | Savor | 3% |
| Popular Streaming | Savor | 3% |
| Everyday Purchases | Venture X | 2X Miles |
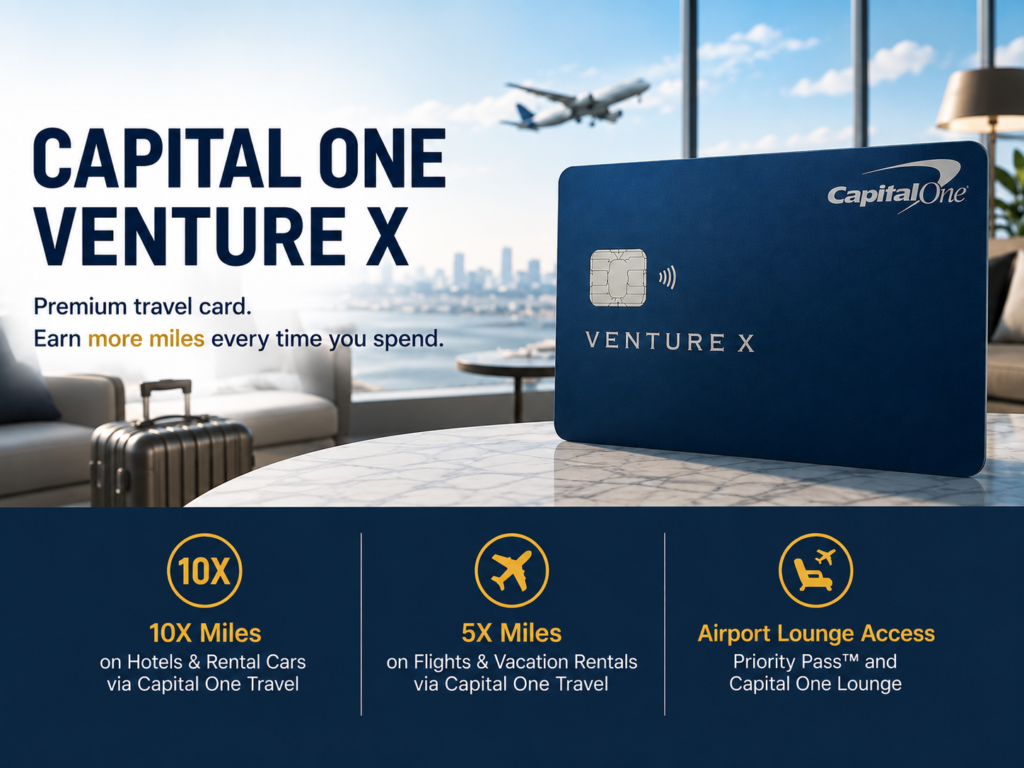
| Capital One Travel | Venture X | Up to 10X Miles |
The strategy is simple:
Savor → Everyday bonus categories
Venture X → Everything else + travel
If you don’t need Venture X’s premium travel benefits, such as airport lounge access and the $300 annual Capital One Travel credit, consider:
Savor + Venture
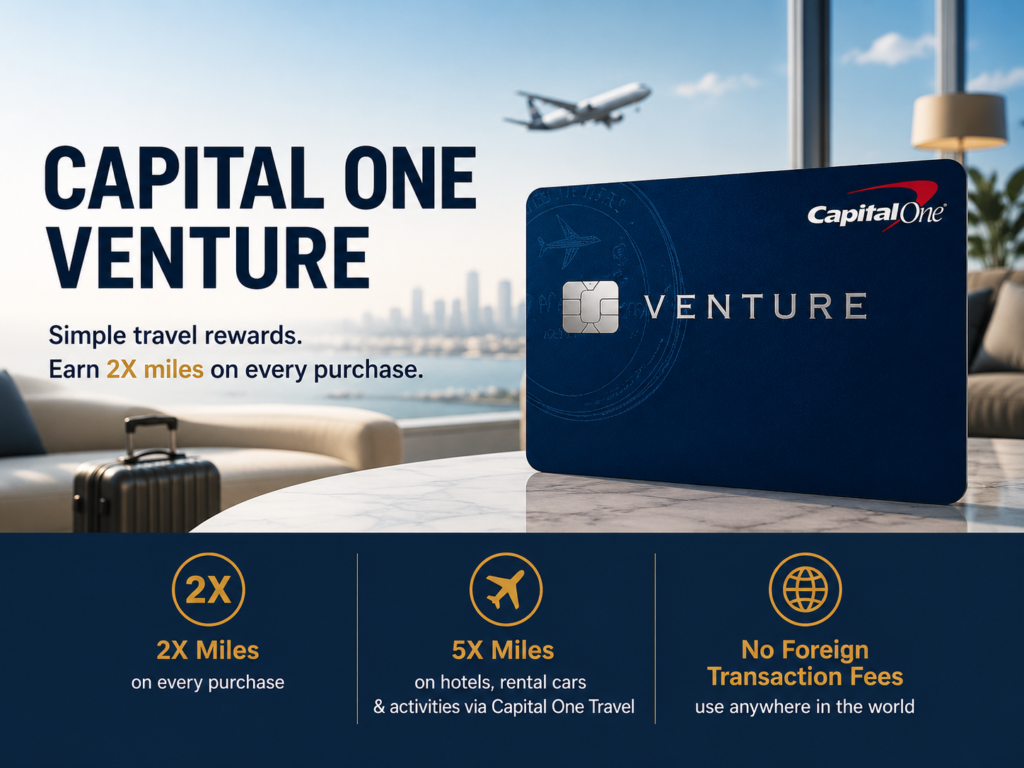
Venture has a lower annual fee while still earning 2X Capital One Miles on everyday purchases.
Bottom Line
The Capital One Savor has a very straightforward value proposition:
$0 annual fee + 3% back on dining, groceries, entertainment & streaming
If you’re primarily interested in cash back, Savor works perfectly well as a standalone card.
But if you want to build a Capital One rewards strategy, my preferred combination is:
Savor + Venture X
Savor handles everyday bonus categories, while Venture X covers non-bonus purchases and travel.
If you don’t need premium travel benefits:
Savor + Venture
is the lower-cost alternative.
Capital One Savor Historical Welcome Offers
| Date | Public Welcome Offer | Minimum Spend |
|---|---|---|
| Before Oct. 2020 | $150 Cash Back | $500 / 3 months |
| Oct. 2020 | $200 Cash Back | $500 / 3 months |
| May 2023 | $200 Cash Back | $1,000 / 3 months |
| Aug. 2023 | $200 Cash Back | $500 / 3 months |
| Oct. 2024 | $250 Cash Back | $500 / 3 months |
| Dec. 2024 | $200 Cash Back | $500 / 3 months |
| Aug. 2025 | $200 Cash Back + $100 Capital One Travel Credit | $500 / 3 months |
| Dec. 2025 | $200 Cash Back | $500 / 3 months |
| Jun. 2026 | $250 Cash Back | $500 / 3 months |
| Aug. 2026 | $200 Cash Back | $500 / 3 months |
Public offers only. Targeted, referral, mail, and other personalized offers are excluded.
👉 Apply for the Capital One Savor Rewards Credit Card
Capital One Miles Credit Card Comparison
Capital One credit cards can be divided into Personal Cards and Business Cards, covering both Cash Back and Capital One Miles rewards.
Capital One Personal Cards
| Credit Card | Annual Fee | Core Role | Foreign Transaction Fee |
|---|---|---|---|
| VentureOne | $0 | Entry-level Miles | 0% |
| Venture | US$95 | Everyday 2X Miles | 0% |
| Venture X | US$395 | Premium Travel + 2X Miles | 0% |
| Savor | $0 | Bonus Category Cash Back / Miles Strategy | 0% |
| Quicksilver | $0 | Everyday Cash Back / Miles Strategy | 0% |
Capital One Business Cards
| Credit Card | Annual Fee | Core Role | Foreign Transaction Fee |
|---|---|---|---|
| VentureOne Business | $0 | Entry-level Business 1.5X Miles | 0% |
| Venture Business | US$95 | Everyday Business 2X Miles | 0% |
| Venture X Business | US$395 | Premium Business Travel + 2X Miles | 0% |
| Spark Cash Select | $0 | No-fee Business Cash Back | 0% |
| Spark Cash | $0 first year / $95 after | Everyday Business 2% Cash Back | 0% |
| Spark Cash Plus | US$150 | High-spend Business 2% Cash Back | 0% |
Application Rules & Restrictions
When applying for Capital One credit cards, keep the following rules and restrictions in mind:
- Hard Pull: Capital One may pull your credit reports from Experian, Equifax, and TransUnion, meaning a single application could result in Hard Inquiries across multiple credit bureaus.
- Pre-Approval: Some Capital One Cards allow you to check for Pre-Approval before submitting a formal application. Checking Pre-Approval generally does not affect your credit score, but a formal application may still result in a Hard Pull.
- Welcome Offer Eligibility: Some Capital One Cards have a 48-Month Rule or Card Family Restrictions. Receiving a Welcome Offer on certain Capital One Cards in the past may affect your eligibility for another Welcome Offer.
- Application Timing: Capital One does not have a simple published rule equivalent to Chase 5/24. Historical Data Points have sometimes suggested roughly six months between applications, but this should not be treated as a fixed official rule.
A simple Capital One application strategy is:
Pre-Approval → Confirm Welcome Offer Eligibility → Submit Application → Hard Pull
Actual application eligibility, credit bureau inquiries, and Welcome Offer Eligibility are subject to Capital One’s current terms for each card.
How Can Foreigners Apply for Capital One Credit Cards?
Foreign applicants generally need to establish some U.S. Credit History before applying for Capital One credit cards.
For someone just entering the U.S. credit card market, one possible strategy is to use Amex Global Transfer to obtain a U.S. Amex card first, establish U.S. credit history, and then consider applying for Capital One.
Amex Global Transfer → U.S. Amex → Build U.S. Credit History → Capital One
Some Capital One Cards also provide a Pre-Approval tool that can help evaluate your likelihood of approval before submitting a formal application. Final approval remains subject to Capital One’s underwriting decision.