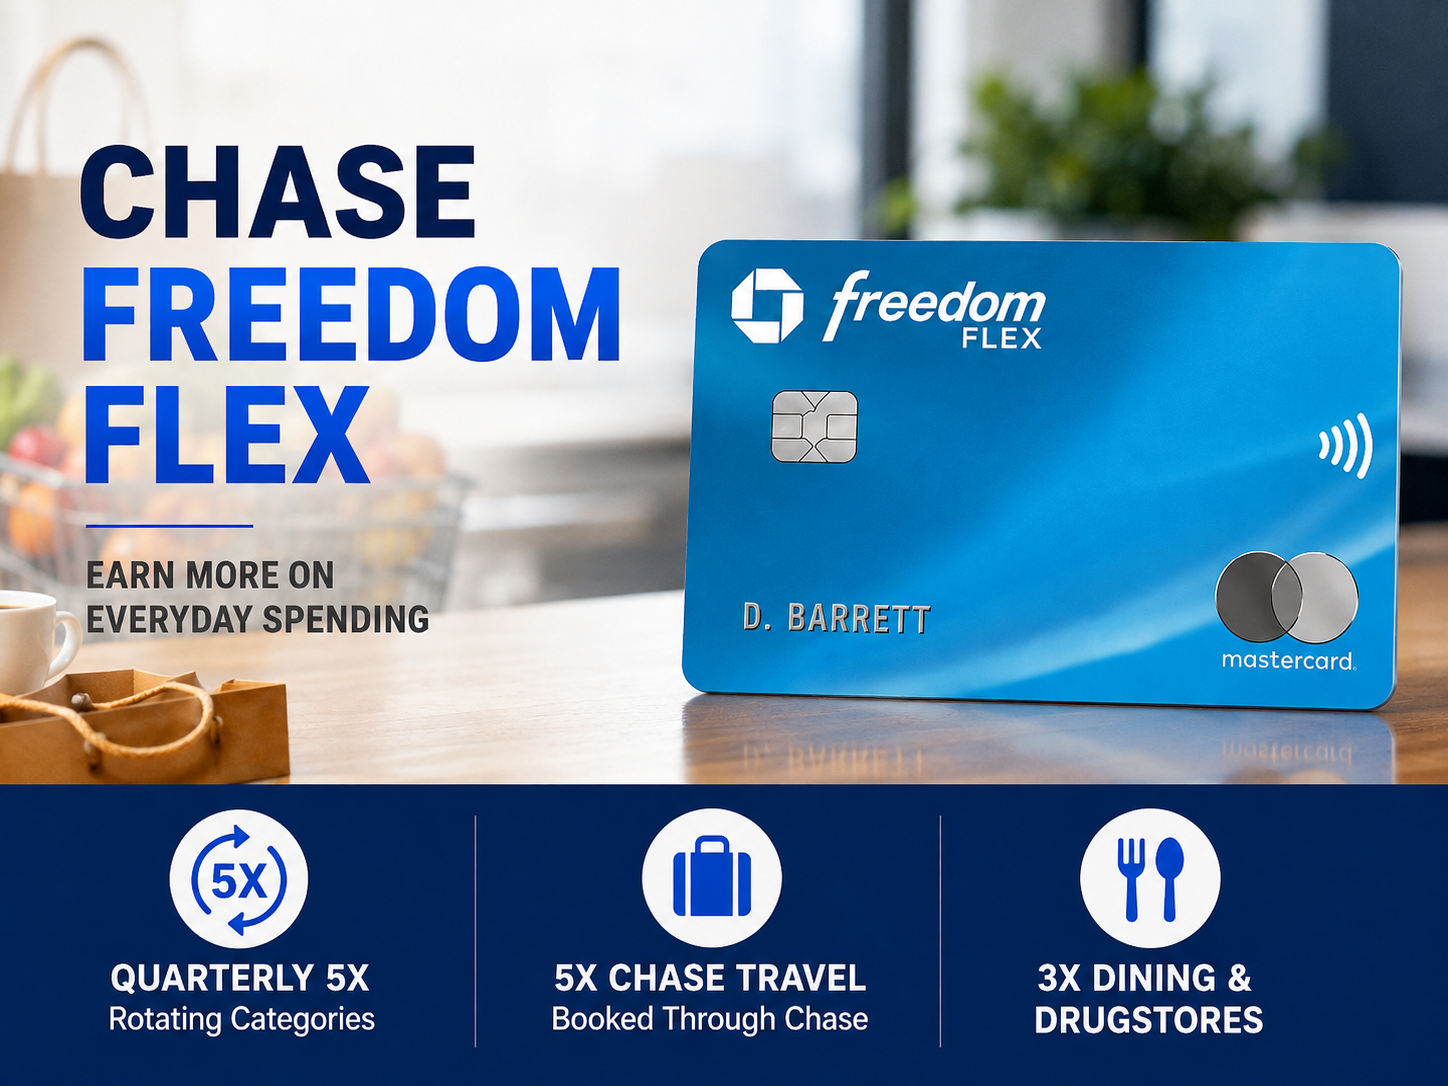

Chase Freedom Flex is a no-annual-fee credit card designed for earning high rewards through rotating quarterly bonus categories.
The card earns 5% cash back (5X Ultimate Rewards Points) on up to $1,500 in combined purchases each quarter in activated bonus categories. It also earns 5X on Chase Travel, 3X on Dining and Drugstores, and 1X on all other purchases.
For Chase Ultimate Rewards users, the biggest advantage is simple: earn up to 5X UR Points without paying an annual fee.
👉 Apply for the Chase Freedom Flex
Chase Freedom Flex Benefits
| Benefit | Chase Freedom Flex |
|---|---|
| Annual Fee | $0 |
| Quarterly Bonus Categories | 5X |
| Quarterly 5X Limit | $1,500 / quarter |
| Chase Travel | 5X |
| Dining | 3X |
| Drugstores | 3X |
| Other Purchases | 1X |
| Rewards Program | Ultimate Rewards |
| Foreign Transaction Fee | 3% |
| Best For | No-fee quarterly 5X UR |
The defining feature of Freedom Flex is its Quarterly 5X Categories.
After activation, eligible purchases in the quarterly categories earn 5X on up to $1,500 in combined spending.
If you maximize all four quarters:
$1,500 × 4 = $6,000 per year
That means up to $6,000 in annual spending can potentially earn 5X through the rotating categories.
The Key Benefit: 5X UR Points With No Annual Fee
Chase markets Freedom Flex as a cash-back credit card, but the rewards are tracked through the Chase Ultimate Rewards system.
For practical purposes:
1% Cash Back = 1X UR
3% Cash Back = 3X UR
5% Cash Back = 5X UR
For points and miles users, Freedom Flex can therefore be viewed as:
$0 Annual Fee + Quarterly 5X UR
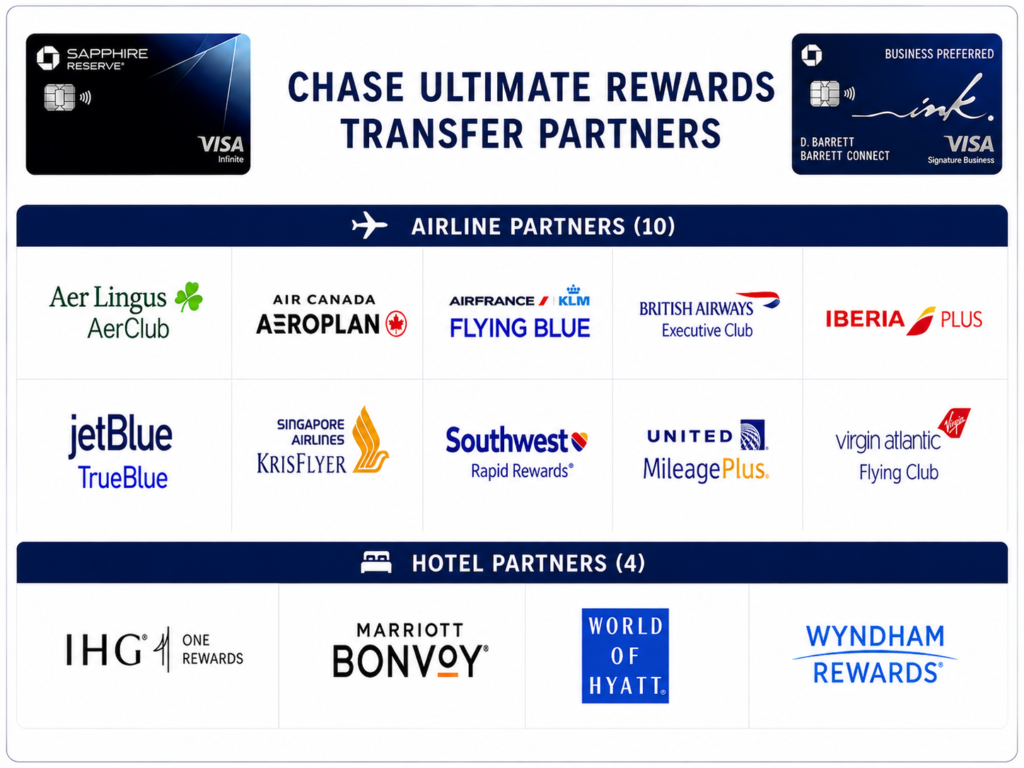
Freedom Flex is particularly useful when paired with an eligible Sapphire or Ink card that provides access to Ultimate Rewards airline and hotel transfer partners.
Freedom Flex handles the earning, while the premium UR card provides additional options for redeeming and transferring the points.
Is the Chase Freedom Flex Worth It?
For anyone building a Chase Ultimate Rewards strategy, Freedom Flex is an excellent long-term card.
Its three main strengths are:
$0 Annual Fee
Quarterly 5X UR
3X Dining & Drugstores
The trade-off is that the quarterly 5X categories require activation and change throughout the year. The 5X rate is also limited to $1,500 in combined eligible purchases per quarter.
Another important limitation is the 3% foreign transaction fee.
That makes Freedom Flex a strong card for bonus-category spending in the U.S., but a poor choice for purchases abroad. For international spending, a Sapphire card or another card with no foreign transaction fees is generally a better option.
Chase Freedom Flex Historical Welcome Offers
| Date | Public Welcome Offer | Minimum Spend |
|---|---|---|
| Sep. 2020 | $200 + 5X Groceries | $500 / 3 months |
| Jan. 2021 | $200 | $500 / 3 months |
| Jul. 2021 | $200 + 5X Groceries | $500 / 3 months |
| Jan. 2022 | $200 | $500 / 3 months |
| Dec. 2022 | $200 + 5X Groceries | $500 / 3 months |
| Sep. 2024 | $150 | $500 / 3 months |
| Oct. 2024 | $200 | $500 / 3 months |
Public offers only. Targeted, referral, branch, mail, and other personalized offers are excluded.
👉 Apply for the Chase Freedom Flex
Chase Ultimate Rewards Credit Card Comparison
Chase credit cards can be divided into Personal Cards and Business Cards, while the Ultimate Rewards ecosystem includes both Cash Back and Points-focused products.
General users can choose cards based on everyday spending, travel, or business expenses. Points and miles enthusiasts can combine different Chase Cards to earn Ultimate Rewards and use cards with Transfer Partner access to build a complete Chase Ultimate Rewards Ecosystem.
Personal Credit Cards
| Credit Card | Annual Fee | Core Role | Foreign Transaction Fee |
|---|---|---|---|
| Freedom Flex | $0 | Quarterly 5X | 3% |
| Freedom Unlimited | $0 | Everyday 1.5X | 3% |
| Freedom Rise | $0 | 1.5X / Build Credit | 3% |
| Sapphire Preferred | US$95 | Travel + UR Transfers | 0% |
| Sapphire Reserve | US$795 | Premium Travel + UR Transfers | 0% |
Business Credit Cards
| Credit Card | Annual Fee | Core Role | Foreign Transaction Fee |
|---|---|---|---|
| Ink Business Cash | $0 | Up to 5X Business Categories | 3% |
| Ink Business Unlimited | $0 | Unlimited 1.5X Business Spending | 3% |
| Ink Business Preferred | US$95 | 3X Business Categories + UR Transfers | 0% |
| Ink Business Premier | US$195 | Large Purchases up to 2.5% Cash Back | 0% |
| Sapphire Reserve for Business | US$795 | Premium Business Travel + UR Transfers | 0% |
Application Rules & Restrictions
When applying for Chase credit cards, keep these key rules in mind:
– 5/24 Rule: If you have opened 5 or more credit card accounts that appear on your personal credit report within the past 24 months, it will generally affect your ability to get approved for a new Chase Card. Most Business Cards that do not report to personal credit reports generally do not add to your 5/24 count.
– Welcome Offer Eligibility: Different Chase Cards have their own Welcome Offer restrictions, and some products also have Card Family Restrictions. Being under 5/24 does not necessarily mean you are eligible for a Welcome Offer.
– Application Timing: Chase does not publish a simple fixed application interval, but submitting multiple Chase applications within a short period may affect approval.
A simple Chase application strategy is:
Check 5/24 → Check Welcome Offer / Family Eligibility → Submit Application
Actual application and Welcome Offer Eligibility requirements are subject to the current terms of each Chase Card.
How Can Foreigners Apply for Chase Credit Cards?
Foreign applicants generally need to establish some U.S. Credit History before applying for Chase credit cards.
If you are new to the U.S. credit card market, one strategy is to first obtain a U.S. Amex through Amex Global Transfer, build your U.S. credit history, and then consider applying for Chase.
Amex Global Transfer → U.S. Amex → Build U.S. Credit History → Chase
Applicants must still meet Chase’s current requirements regarding identification, address, credit history, and other application criteria.